Mortgage myths can lead to costly decisions. Explore 10 common UK mortgage misconceptions and learn what borrowers should know about deposits, credit scores, interest rates, remortgaging and mortgage costs.
Mortgage decisions can affect your finances for decades, yet many borrowers approach them with assumptions that are not quite right. Some myths sound harmless, such as believing you need a large deposit or that a fixed-rate mortgage is always the cheapest option.
Others can lead to expensive mistakes, particularly when choosing a product, applying for a mortgage or deciding whether to remortgage.
Here are 10 common mortgage myths in the UK, along with what you should consider instead.
1. You need a 20% deposit to get a mortgage
A 20% deposit can give you access to a wider range of mortgage products, but it is not a universal requirement.
Some mortgages are available with deposits of 5% or 10%, although a smaller deposit can affect the interest rate and the range of products available. The amount you can borrow also depends on your income, outgoings, credit history, the property and the lender’s criteria.
For example, someone with a £250,000 property and a 5% deposit would need to borrow £237,500. A larger deposit could reduce the amount borrowed and potentially improve the mortgage options available.
The useful question is not simply “How much deposit do I need?” It is “How does my deposit affect the mortgage products and overall cost available to me?”
2. A high credit score guarantees mortgage approval
A strong credit history can help, but there is no single credit score that guarantees a mortgage application will be accepted.
Mortgage lenders assess your wider financial circumstances. They can consider your income, existing debts, regular expenditure, employment situation, deposit, the property and their own lending criteria.
Your credit report is also different from the score you see through a credit reference agency or credit monitoring service. A lender may use its own assessment alongside information from credit reference agencies.
This is why someone with an apparently excellent credit score can still be declined, while another applicant with a less impressive score may be accepted.
Before applying, check your credit reports for errors and make sure your financial information is accurate.
3. An Agreement in Principle means your mortgage is approved
An Agreement in Principle, also called a Decision in Principle or Mortgage in Principle, is useful when planning a purchase, but it is not a formal mortgage offer.
It provides an indication of how much a lender might be prepared to lend based on the information available at that stage. The lender can still carry out further affordability checks, verify your income and assess the property before making a formal offer.
This distinction matters because a buyer who assumes an AIP is guaranteed could commit to a property budget that later proves unsuitable.
Use an AIP as an indication of your potential borrowing capacity, not as confirmation that the mortgage is secured.
4. The mortgage with the lowest interest rate is always the cheapest
The headline interest rate is important, but it is only one part of the cost.
A mortgage with a lower rate could have a substantial product fee, while a fee-free mortgage might come with a higher rate. You also need to consider valuation fees, legal costs where applicable, early repayment charges and other product conditions.
Suppose two mortgages have similar rates but one has a £1,000 product fee. Depending on the loan size and mortgage term, paying the fee may or may not make financial sense.
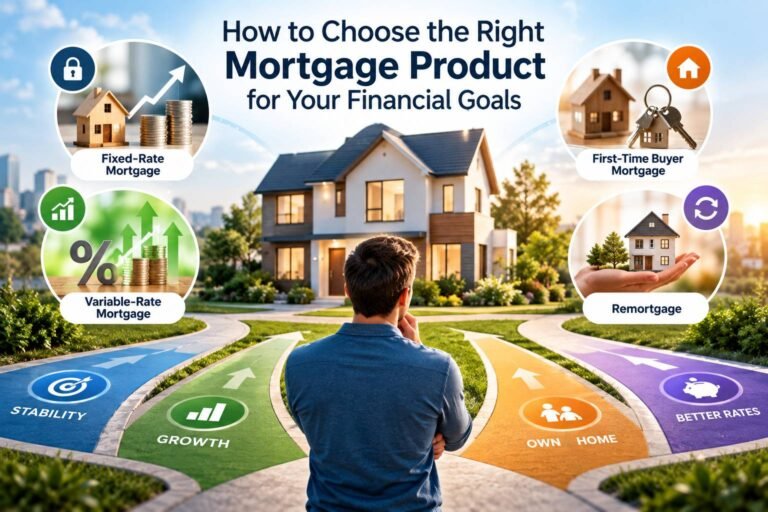
Look at the overall cost of the deal rather than comparing interest rates in isolation. If you need help assessing your options, researching the Right Mortgage Product can help you understand the factors that should be considered before choosing a deal.
5. A fixed-rate mortgage means your mortgage payments can never change
A fixed-rate mortgage normally means the interest rate is fixed for a specified period. It does not mean your mortgage payment is guaranteed to remain unchanged for the entire mortgage term.
For example, a two-year fixed mortgage normally fixes the rate for two years, after which you may move onto the lender’s follow-on rate unless you arrange another deal.
Your monthly payment can also be affected by changes to other costs associated with home ownership, such as buildings insurance, energy bills and Council Tax.
The key point is to distinguish between the fixed-rate period and the overall mortgage term.
6. You can remortgage whenever you want without any extra cost
You can explore remortgage options before your current deal ends, but switching at the wrong time can involve costs.
An early repayment charge may apply if you leave certain fixed or discounted-rate mortgages before the end of the relevant deal period. The amount depends on the terms of your mortgage.
There may also be product fees, legal costs, valuation costs or other expenses associated with the new mortgage.
That does not mean remortgaging early is always a bad idea. If a new deal produces enough savings to outweigh the costs, it could be worth considering. The calculation needs to account for all relevant charges rather than just the new interest rate.
If your existing deal is approaching its end, Remortgage Advice in Southend-on-Sea is one example of the type of specialist advice available to borrowers reviewing their options.
7. Overpaying your mortgage is always the best use of spare cash
Paying extra towards your mortgage can reduce the outstanding balance and, depending on the mortgage terms, reduce the interest you pay over time. But it is not automatically the best financial choice in every situation.
First, check whether your mortgage places limits on overpayments or charges you for exceeding them. Some mortgages allow a certain level of annual overpayment without an early repayment charge, but the exact terms vary.
You also need to consider your emergency savings. Using all your spare cash to reduce the mortgage could leave you without enough money to deal with an unexpected expense.
There may also be other priorities, such as paying off expensive unsecured debt or maintaining adequate pension and savings contributions.
Overpaying can be valuable, but it should form part of your wider financial plan.
8. Self-employed applicants cannot get competitive mortgages
Being self-employed does not automatically prevent you from obtaining a mortgage. The challenge is usually demonstrating income clearly enough for a lender to assess affordability.
Lenders can have different requirements for self-employed applicants. They may request accounts, tax calculations, tax year overviews, bank statements or other evidence, depending on the circumstances.
The way your income is structured can also matter. A sole trader, company director and contractor may be assessed differently by different lenders.
If you are self-employed, preparation is particularly useful. Having your financial records organised before applying can make it easier to identify lenders whose criteria fit your circumstances.
9. First-time buyers should choose the mortgage with the smallest monthly payment
A low monthly payment can look attractive, particularly when you’re working within a tight household budget. It should not be the only measure you use.
A longer mortgage term can reduce the required monthly repayment, but it can also mean paying interest over a longer period. The product itself may also have different fees, rates and repayment conditions.
First-time buyers should consider both immediate affordability and the longer-term cost of borrowing.
For buyers in Essex, for example, First-Time Buyer Mortgages in Grays illustrates the type of local mortgage support available when comparing first-time buyer options.
The right mortgage needs to fit the household budget without creating unnecessary long-term costs.
10. A mortgage broker will always charge you a large fee
Mortgage broker charges vary. Some brokers charge a fee, some are paid through commission from the lender, and some use a combination of approaches. The exact arrangement should be explained before you proceed.
The value of advice should therefore be considered alongside the cost. A broker may help you understand different mortgage products, lender criteria and application requirements, but you should still ask how the adviser is paid and what services are included.
If you are comparing mortgage advice locally, you may come across services such as mortgage broker london or Professional Mortgage Advice in Rainham. The important point is to understand the adviser’s fees, scope of service and lender access before committing.
For first-time buyers, specialist guidance can also be useful where circumstances are less straightforward. For example, First-time buyer mortgage advice Rayleigh focuses on support for buyers in that local area.
Also Read: How a Commercial Mortgage Broker Can Help Your Business Secure Better Finance
How to avoid expensive mortgage mistakes
The biggest mortgage mistakes often happen when a borrower focuses on one figure rather than looking at the whole deal.
Before choosing a mortgage, consider:
- the interest rate and how long it applies
- the overall product and arrangement fees
- the size of your deposit
- the mortgage term
- early repayment charges
- overpayment rules
- your expected changes in income or expenditure
- whether the mortgage remains affordable if circumstances change
- the total cost over the relevant period
It is also worth remembering that lenders have different criteria. A mortgage that works for one borrower may not be suitable for another, even when their incomes appear similar.
A sensible mortgage decision starts with your financial circumstances and future plans, then compares products against those requirements. Do not let a low advertised rate, a large borrowing figure or a commonly repeated mortgage myth make the decision for you.
Before signing up, read the mortgage illustration and check the fees, rate period, repayment structure and conditions carefully. If anything is unclear, ask the lender or a qualified mortgage adviser to explain it.
Published by Meedium.